Macro Notes - An Update on the Two AI Risks
October 15, 2026
Earlier in August, we flagged two AI-related risks to watch for. The first was the degree of leverage for the larger neoclouds, and the second was the stability of revenues for frontier labs.
Yesterday, both of those risks were reflected as shares in the neocloud firm, CoreWeave, plunged by over 15% while its 5-year CDS spread spiked to 1130bps. The latter implies a market-implied estimate of greater than 50% chance of default over the next 5 years.
While higher bond yields following the US CPI print feel like the most proximate catalyst, the move reflects the two risks that we flagged in August:
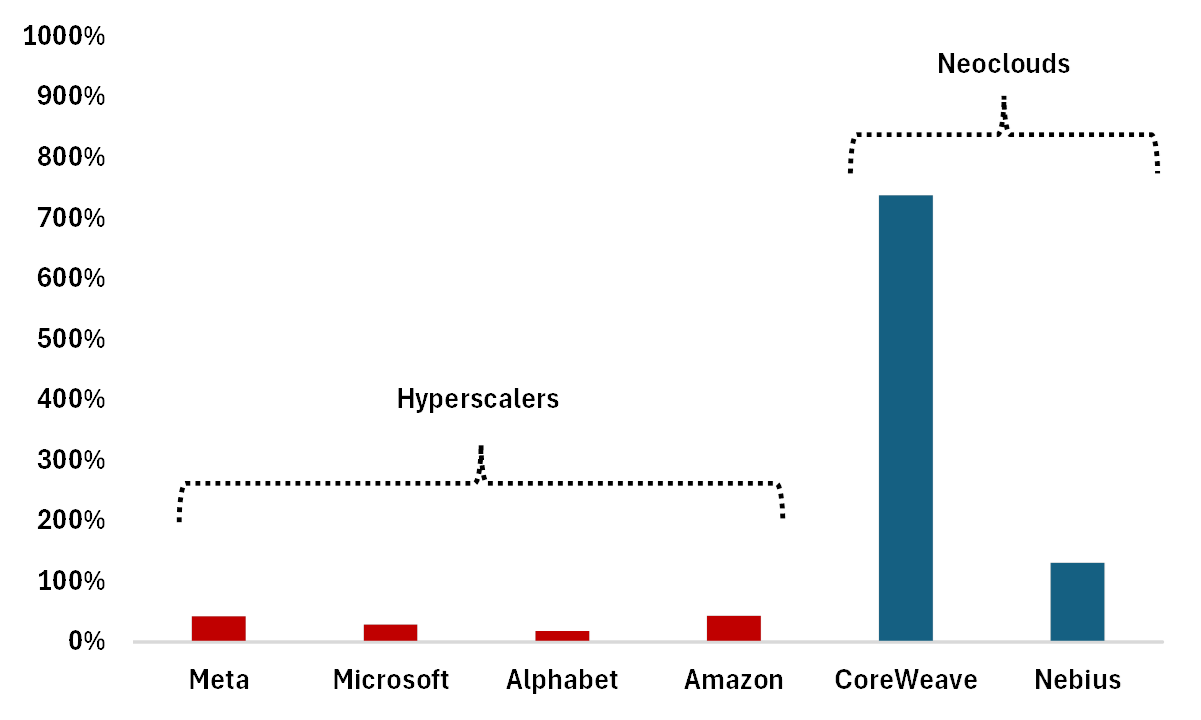
- CoreWeave’s debt-to-equity ratio is over 700% - well above the levels of other hyperscalers. And remember that CoreWeave doesn’t have the same diversified stream of revenues as those other firms.
- Recall that the debt raised by neoclouds (like CoreWeave) to finance GPU purchases is supported by long-term agreements with frontier labs. However, revenues from those same frontier labs are exposed to the commodification of AI models.
I wouldn’t say that this is the tipping point for CoreWeave or other neoclouds – not least as the ratio of gross debt to revenue backlog doesn’t indicate stress. However, yesterday was a signal that the risks of the AI trade are coming into sharper relief.
The risks to the AI trade are asymmetric from here. Indeed, this is the right time to take on insurance for your portfolios. Two products that fit that framework include ZOCT and ZCDX.
Chart 1 – Gross Debt-to-Equity: Hyperscalers vs Neoclouds